David Team Homes · 5 minute read · Updated
The short answer
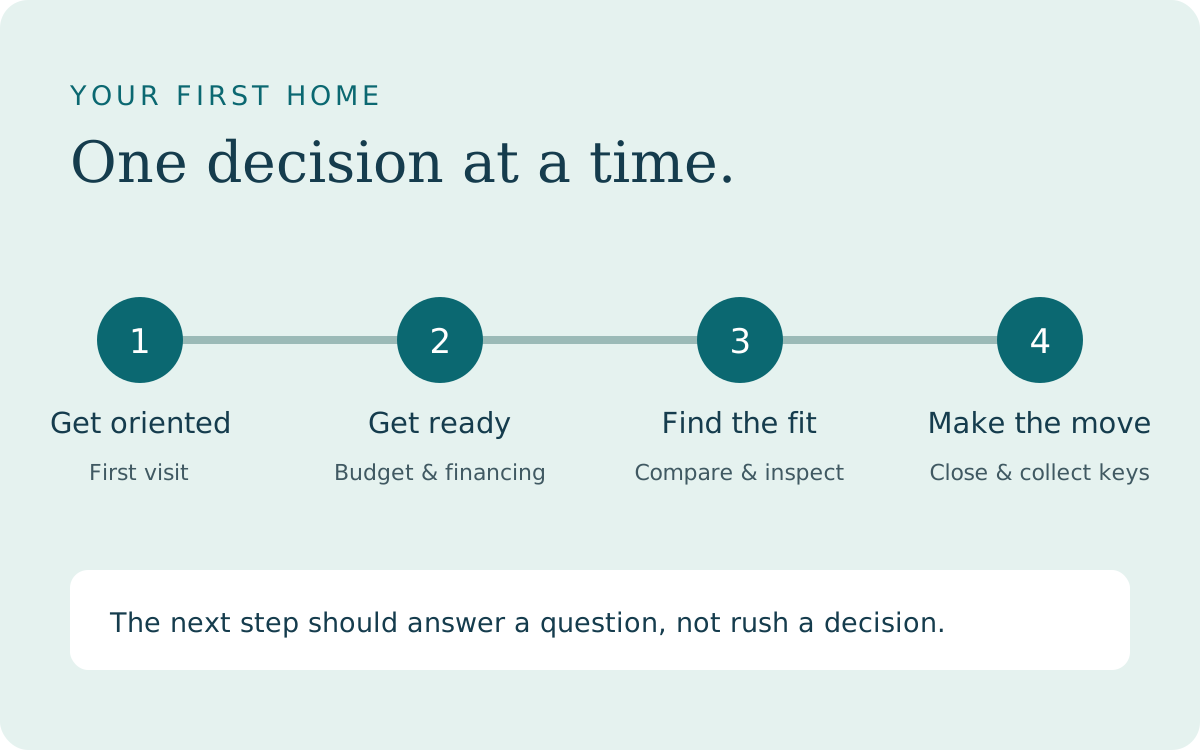
Start with a comfortable budget and a lender conversation, then narrow your search. For a first showing, understand the written agreement for that visit. Before a broader search and offers, clarify financing, representation, the cash you may need and the deadlines a contract creates. The search is only one part of buying; the inspections, financing and closing matter just as much.
1. Work backward from a payment you can live with
A lender’s maximum and your comfortable monthly budget can be different numbers. Ask for an estimate that includes taxes, insurance, any association dues and mortgage insurance when applicable. Leave room for maintenance and ordinary life. For lending terms and eligibility, rely on your lender’s current written information.
2. Separate must-haves from nice surprises
Pick a small list of things the home has to do for you. Think about space, your daily routes, accessibility needs you want to discuss, outdoor use and the work you’re willing to take on. Then browse across your price range. That gives you a better feel for tradeoffs than falling in love with one photo.
3. Know how you’ll work with an agent
Our usual starting point is one showing with a single-property agreement, which can happen before you have a pre-approval. It is a chance to see the home and get to know each other. Before an ongoing search, we work through financing readiness and the appropriate representation agreement. Discuss services, compensation and how questions will be handled before signing. Ask what you would pay in different situations. Don’t assume a seller will cover a cost that has not been agreed in writing.
Have cash ready for more than the down payment
Ask your lender and closing provider to separate the down payment, closing costs, prepaid items and funds due earlier in the process. Inspection and other service charges may come before closing. Keep moving costs and a repair reserve in your own budget as well. Use written estimates for your situation rather than a general percentage.
Leave each showing with three answers
What works, what would you change, and what needs verifying? A room can photograph well and still be the wrong layout for your furniture or daily routine. Write down those answers while the home is fresh in your mind. Send us the questions that could change your decision before scheduling another visit or preparing an offer.
4. Compare the offer terms, not just the price
The deposit, inspection rights, financing, appraisal, closing date and possession can all matter. Understand what money is due, when decisions are required and what happens if a condition is not met. Your agent can help explain the process; contract or legal questions may need broker or attorney guidance.
5. Use the contract period to verify
Inspection, insurance availability, financing and title review can reveal things photos do not. Keep the dates visible and respond to document requests promptly. A pre-approval is not final loan approval. Before changing debt, employment or moving funds, check with your lender.
6. Prepare for closing and possession
Review the closing figures with the right professionals, confirm the final walkthrough, and understand when you receive possession. Verify any wiring instructions directly with the title company using a trusted phone number. An unexpected email changing payment instructions deserves a phone call.
You do not have to know everything before you start. You should understand each decision before it becomes your commitment.
For the lending and closing details, the Consumer Financial Protection Bureau has a useful homebuying resource library and Closing Disclosure explainer.
Want to talk about your situation?
Your email or messaging app opens with a short draft. Add what you want us to know and send when you’re ready. Prefer another device? jeremy@davidteamhomes.com